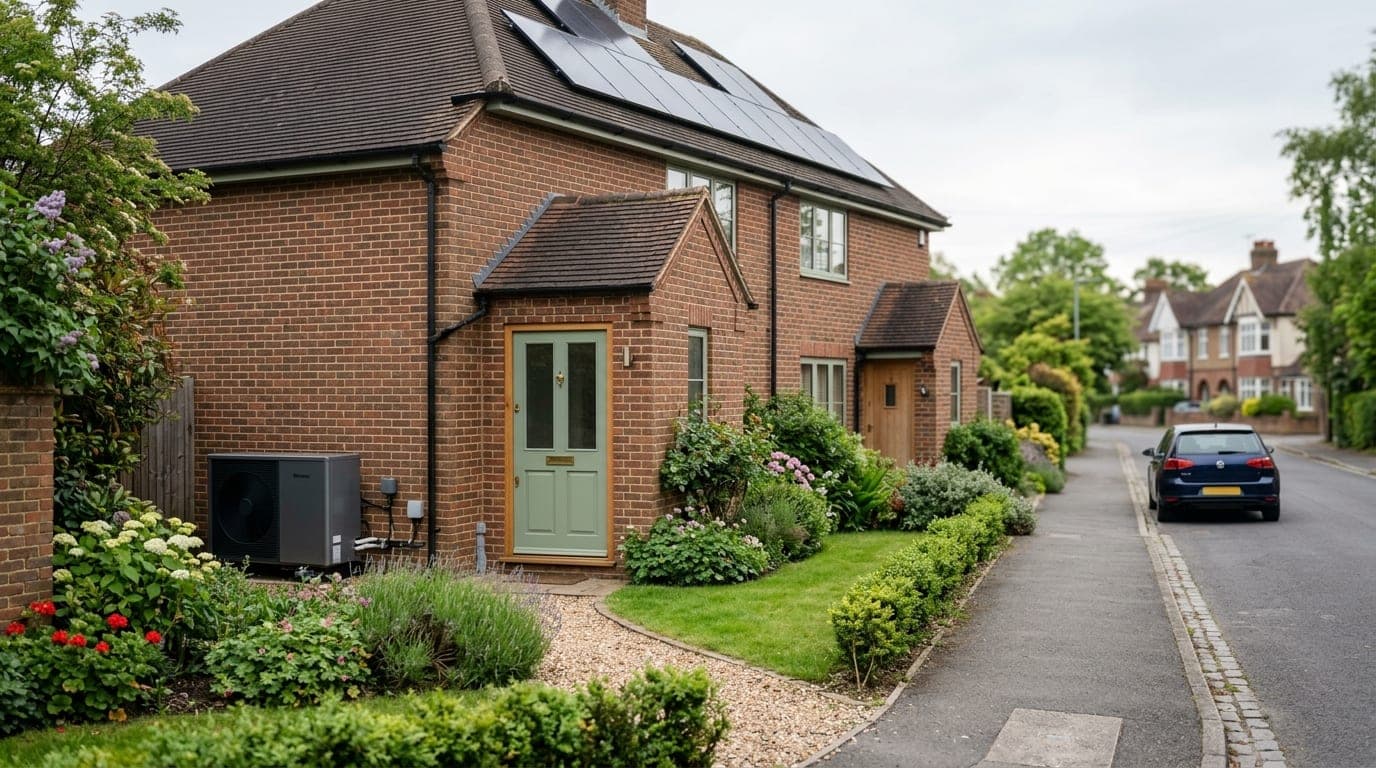
A green mortgage is a mortgage, or extra borrowing on one, that gives you a benefit for owning an energy-efficient home or for improving one. The benefit is usually a lower rate or cashback if the property has an EPC rating of A or B, or cheaper borrowing and cashback for energy-saving work such as solar panels or a heat pump.
The rules differ a lot between lenders. Some need a new-build. Some need a score at the top of band B. Some pay you for the improvement and ignore your EPC. This guide sets out what each major lender says on its own website, then covers how your EPC affects a mortgage application and how buy-to-let lenders use it.
Lender details checked on 30 September 2026. Offers change without notice, so confirm on the lender's page before you rely on anything here.
This is general information, not mortgage advice. Speak to a mortgage adviser about your own circumstances.
What Is a Green Mortgage?
There is no legal definition of a green mortgage. Lenders use the label for three main types of product:
- Rate reduction or cashback for an efficient home. Usually for properties rated EPC A or B, and sometimes A to C. The lender looks at the certificate on the government register, not at what you plan to do with the house.
- Extra borrowing or cashback for improvements. You borrow more on your mortgage, or receive cash, to pay for insulation, solar panels, a heat pump or similar. The EPC rating of the home is often not the test.
- Enhanced borrowing. Some lenders offer higher income-to-loan ratios for A or B rated homes, according to Which? (page updated 29 May 2026).
You will also see these called eco mortgages or energy efficient mortgages. Which? makes the point that green mortgages are not "green" in themselves. A lender does not have to prove the mortgage has any environmental effect.
The Green Finance Institute says the number of green mortgage products grew from 4 in 2019 to over 90. It keeps a quarterly-updated hub of products and providers.
Green Mortgage Lenders: What Each Offers
Each lender below was checked against its own page on 30 September 2026. Amounts and eligibility are quoted from that page. We do not quote interest rates, because they change weekly. Check the lender's current rate on the lender's page or with an adviser.
Nationwide Green Mortgage Offer: Green Reward
Nationwide's Green Reward pays cashback when you buy an energy-efficient home with a Nationwide mortgage. You must be buying as a first-time buyer or a home mover.
- £500 cashback for a property with an EPC score of 92 or above.
- £250 cashback for a property with a score of 86 to 91.
- The EPC must be on the government register within 2 weeks of your mortgage completing. Nationwide checks the score two weeks after completion and pays the cashback 4 weeks after completion.
Note the score bands. Band B runs from 81 to 91, so a B rated home at 84 would not qualify. Nationwide also says the cashback is available in addition to its other cashback offers, and that it is not responsible for the registration or accuracy of the EPC.
Nationwide also offers Green Additional Borrowing to existing Nationwide mortgage customers. You can borrow £5,000 to £20,000 with 0% fixed interest for the first 2 or 5 years. Your combined borrowing cannot exceed 90% of your home's value, and 100% of the loan must go on energy-efficiency improvements. It cannot pay for work already done.
Virgin Money's consumer "greener mortgages" page now redirects to Nationwide's Green Reward page, so check which brand's terms apply to you.
Barclays Green Home Mortgage
The Barclays Green Home Mortgage offers a lower rate on certain fixed-term deals. It is for residential buyers of a new-build property bought directly from the builder or developer. The property needs an energy efficiency rating of 81 or above, or to be in bands A or B. You provide an EPC, or a Predicted Energy Assessment (PEA) if the home is still being built.
It is not an offer for existing homes. Barclays' Green Home Mortgage page does not state the size of the rate reduction.
Barclays Greener Home Reward
The Barclays Greener Home Reward is a one-time cash reward for improvements, not a lower rate. It does not depend on your EPC band.
- £1,000 for low carbon heating: an air source heat pump, a biomass pellet boiler or a ground source heat pump.
- £500 for solar: solar battery storage, solar panels or solar thermal hot water.
- You need an eligible residential Barclays mortgage on your main home, an installer certified under the Microgeneration Certification Scheme (MCS), and an MCS certificate dated within three months of your claim.
- Buy-to-let mortgages are not eligible. Barclays' FAQ says you cannot claim for improvements to buy-to-let properties or holiday homes.
Barclays also states there is no guarantee that the improvements will raise your EPC rating, and that claiming the reward does not mean you will qualify for a Green Home Mortgage. The reward is sometimes searched for as the Barclays green home reward. It is also not the Greener Home Loan, which is an unsecured personal loan of £1,000 to £50,000 for Barclays current account customers, not a mortgage.
NatWest Green Mortgage
NatWest Green Mortgages give a lower interest rate on selected 2-year or 5-year fixed products marked "Green Mortgage" or "Green Remortgage". The property needs a valid EPC rating of A or B, and you can be buying or remortgaging.
- Residential green mortgages go up to 85% loan to value (LTV).
- New-build homes bought within two years of construction also qualify.
- Product fees and early repayment charges may apply, and NatWest says the offer can be changed or withdrawn at any point.
NatWest's page does not state the size of the rate reduction.
HSBC Energy Efficient Home Mortgage
HSBC's energy-efficient home mortgages pay cashback on completion on selected products. The property needs an in-date EPC, or a PEA for a new-build under construction, rated A or B. You can be a first-time buyer, a home mover or remortgaging to HSBC.
HSBC says the cashback amount depends on the product and the LTV, so read the rate tables on its page for the current figures. HSBC also lists buy-to-let criteria on the same page, covered in the buy-to-let section below.
Virgin Money Greener Mortgages
Virgin Money's broker lending criteria say its Greener mortgages are for people "purchasing a new build residential home with a certified or predicted energy rating of A or B". Evidence is an EPC, a PEA or a SAP calculation. Virgin Money says these products are priced more competitively than the equivalent non-Greener product. The page does not state the size of the difference.
Lenders not listed
Halifax, Santander and Paragon Bank are not listed in this guide. We could not confirm a current product on each lender's own page on 30 September 2026, because the page either would not load for us or was a press release from an earlier year. That is not the same as saying they do not offer one. Check their sites or ask an adviser.
The seller’s actual EPC is free to look up
The property you are buying should already have a certificate, and anyone can look it up for free on the official register. Search by address on our EPC checker.
Look up the seller’s EPCPre-purchase energy report: coming soon
We are looking at a report that explains what a property’s energy rating could mean for you before you buy. It is not available yet. Leave your email and we will tell you if it launches.
Green Mortgage Rates: What to Check
Most of the lender pages above say "lower rate" without giving a figure for the discount. The discount is set on each product and moves with the market. A lower rate can also come with a higher product fee, so compare the total cost over the fixed term and not the headline rate.
Before you apply:
- Check the lender's current rate for the exact product, not an old press release or comparison table.
- Check the EPC band or score rule. Nationwide needs 86 or more, which is the upper end of band B.
- Check whether the offer is for purchases only, remortgages only, or both.
- Check fees and early repayment charges. NatWest, for one, says both may apply.
Does Your EPC Rating Affect Whether You Can Get a Mortgage?
For a home you will live in, we did not find a lender page that refuses a residential mortgage because of a low EPC band. The evidence we found runs the other way: lenders use a good EPC to give a benefit, not a bad one to block you. Examples are the Nationwide, NatWest and HSBC offers above, and the enhanced income-to-loan ratios some lenders offer for A or B rated homes, reported by Which?.
A lender will still want the property to have a valid EPC. HSBC says you need not submit the EPC with your application, but the property must have one rated A or B to get its energy-efficient cashback.
Buy-to-let is different. Some buy-to-let lenders do set a minimum:
- Virgin Money says "All BTLs must have a minimum EPC rating of E" in its buy-to-let criteria.
- The Mortgage Works says that for applications above 75% LTV, "the property must have an Energy Performance Certificate (EPC) rated C or above", and that applications that do not meet this are declined (general criteria).
- Shawbrook says in its guide for landlords: "Some lenders will factor EPC into their lending decisions and therefore landlords with properties with low EPC ratings may start to struggle to secure a mortgage."
Lender policy changes, and each lender applies its own rules. If your property is rated D or below, ask an adviser which lenders will consider it before you pay for a valuation.
Green Buy-to-Let Mortgages
A green buy-to-let mortgage rewards a landlord for owning an efficient property, usually with a lower rate, a fee discount or cashback. Each lender below was checked on its own page on 30 September 2026.
| Lender | Product and EPC rule | Benefit as stated by the lender | Lender page |
|---|---|---|---|
| Barclays | Green Buy to Let. Rating of 81 or above, or bands A or B. Only for a new-build bought directly from the builder or developer | "A lower mortgage rate on certain deals" | Barclays |
| NatWest | Green Buy to Let. Valid EPC of A or B. Up to 75% LTV, or 65% for new-build flats or houses | Lower rate on selected 2-year or 5-year fixed products | NatWest |
| HSBC | Energy-efficient home buy-to-let products. EPC or PEA rated A or B. Applicant must have owned and lived in their current home for at least 6 months, will hold no more than 3 buy-to-let mortgaged properties, and earn at least £25,000 a year excluding rental income | EEH cashback. The buy-to-let products listed on the page showed £350 when checked | HSBC |
| Coventry Building Society | Buy-to-let products marked "EPC A-C". Valid EPC of A, B or C (PEA for new-builds). Purchase and remortgage only | "Access to great rates". No discount figure is stated | Coventry |
| Shawbrook | Energy Efficiency Discount. Property with an EPC of at least C, on a new mortgage | Arrangement fee discount of 0.60% for band A, 0.45% for B and 0.25% for C. A partial refund on the same percentages if the EPC improves during the mortgage | Shawbrook |
| Bank of Ireland UK | Energy Efficient buy-to-let range, through brokers. EPC A to C. Purchase and remortgage, up to 75% LTV | Products "could offer your clients better rates or incentives" than its standard range. The EPC must be in place before the valuation | Bank of Ireland |
| The Mortgage Works | Energy Efficiency Further Advance, for existing The Mortgage Works landlords. £2,500 to £15,000, up to 75% LTV. 100% must be spent on eligible improvements | Lower initial rate than its standard further advance range, and no product fees | The Mortgage Works |
Three points from the table:
- None of these lenders states the size of a rate discount. Shawbrook gives its benefit as an arrangement fee discount, and HSBC's buy-to-let products showed £350 cashback when checked.
- Band C is enough at Coventry, Shawbrook and Bank of Ireland UK. It is not enough for Barclays or NatWest.
- Barclays' green buy-to-let product is open only to a new-build bought from the developer. A landlord with an existing rental cannot use it.
Why EPC Matters to Buy-to-Let Lenders
The lender pages above show three ways lenders use EPC: a product only open to A to C properties, a discount that grows with the band, and a loan-to-value limit for lower bands. The Mortgage Works, for example, will not lend above 75% LTV unless the property is rated C or above. A D or E rated property therefore needs a larger deposit or equity share there.
The lender pages we checked do not say why they do this. Our reading is that lenders are pricing in the proposed change to the rental standard, but that is our inference and not something the lenders state.
The rules on letting are separate from lending. In England and Wales, the minimum standard for letting a property is currently EPC band E. A property rated D or E is legal to let today. The government has decided, but not yet legislated, that all in-scope tenancies must meet a new standard by 1 October 2030. It is usually described as EPC C, but it is a dual-metric standard, and it needs an Act of Parliament and then a statutory instrument. See the government response of 21 January 2026 for the decided policy. Our EPC C 2030 deadline guide and our guide to buy-to-let mortgages and EPC cover it in detail.
If you have improved a rental since its certificate was issued, the certificate will not show that. A new assessment records the current state of the property, and it can move the property into a band that more lenders accept.
How to Check a Property's EPC Before You Apply
Check the EPC before you pick a product. Lenders read the certificate on the government register, so what the register shows is what counts.
- Find the certificate. Search the address on the government's Find an energy certificate service, or follow our step-by-step guide to finding an EPC by property lookup.
- Read the band and the score. Some offers use the score, not the band. Nationwide's £250 tier starts at 86, for example.
- Check the date. An EPC lasts 10 years. See how long an EPC lasts. If you have made improvements since it was issued, the certificate may understate the property.
- For a new-build, ask the builder for a Predicted Energy Assessment. Barclays, HSBC and Virgin Money all accept one.
- If there is no certificate, or it is out of date, you can request an accredited energy assessor to produce a new one. Bank of Ireland UK, for example, says a new assessment is needed before the valuation if the EPC is missing or expired.
Frequently Asked Questions
What is a green mortgage? A green mortgage is a mortgage, or additional borrowing on a mortgage, that gives a benefit for an energy-efficient home or for energy-saving improvements. The benefit is typically a lower rate or cashback. Lenders set their own rules, so the EPC requirement and the size of the benefit differ by product.
Which UK lenders offer green mortgages? On 30 September 2026 we confirmed products on the lender's own page for Nationwide, Barclays, NatWest, HSBC and Virgin Money (residential), and for Barclays, NatWest, HSBC, Coventry Building Society, Shawbrook, Bank of Ireland UK and The Mortgage Works (buy-to-let or landlord borrowing). Other lenders may also offer them. Lender details checked on 30 September 2026.
Is there a minimum EPC rating for a mortgage? For a residential mortgage, we did not find a lender page that sets a minimum EPC band. For buy-to-let, some lenders do. Virgin Money requires band E or above, and The Mortgage Works requires C or above for applications above 75% LTV. Ask the lender or an adviser about your case.
Does a buy-to-let mortgage depend on EPC rating? It can. Lenders use EPC to set eligibility for green products, to apply discounts and, at some lenders, to limit loan to value. The letting rules are separate: in England and Wales the current legal minimum for letting is band E, and the proposed 2030 standard is decided policy, not yet law.
Is EPC C good enough for a green mortgage? It depends on the lender. NatWest, HSBC and Barclays' Green Home Mortgage need A or B (Barclays also accepts a score of 81 or above), and Nationwide's Green Reward needs a score of 86 or more. Nationwide's Green Additional Borrowing and Barclays' Greener Home Reward do not depend on the EPC band. Among the buy-to-let lenders above, Coventry, Shawbrook and Bank of Ireland UK accept band C.
What is the Barclays Greener Home Reward? It is a one-time payment of £500 or £1,000 for certain improvements, paid to Barclays residential mortgage customers: £1,000 for low carbon heating and £500 for solar. You need an MCS certificate dated within three months of your claim. It is not available for buy-to-let properties and it does not depend on your EPC band.
Does Nationwide offer a green mortgage? Nationwide's Green Reward pays £500 cashback if you buy with a Nationwide mortgage a property with an EPC score of 92 or above, or £250 if the score is 86 to 91. It also offers Green Additional Borrowing at 0% for the first 2 or 5 years to existing mortgage customers, for energy-efficiency improvements.
Are green mortgage rates lower? Lenders describe them as lower rates on certain deals, but most do not publish the size of the discount on their green pages. Check the lender's current rate and compare the fees and the total cost over the fixed term.
Do I need a new EPC after making improvements? A certificate shows the state of the property on the date of the assessment. If you have made improvements and want a lender to see them, you need a new assessment. You can request an accredited energy assessor.
Where can I get advice on a green mortgage? A mortgage adviser can tell you which products suit your circumstances. This article is general information and not advice.